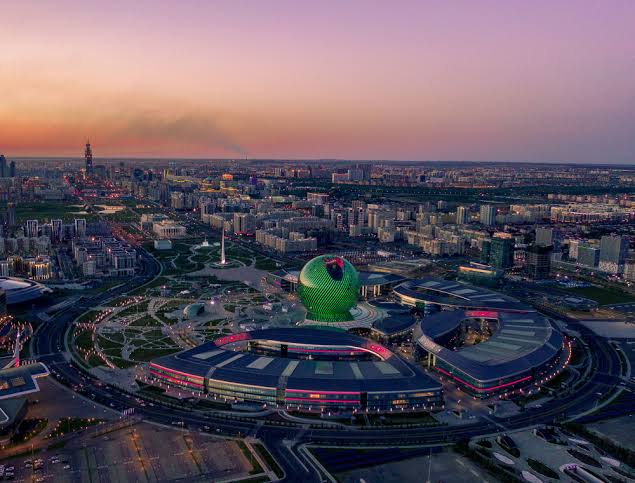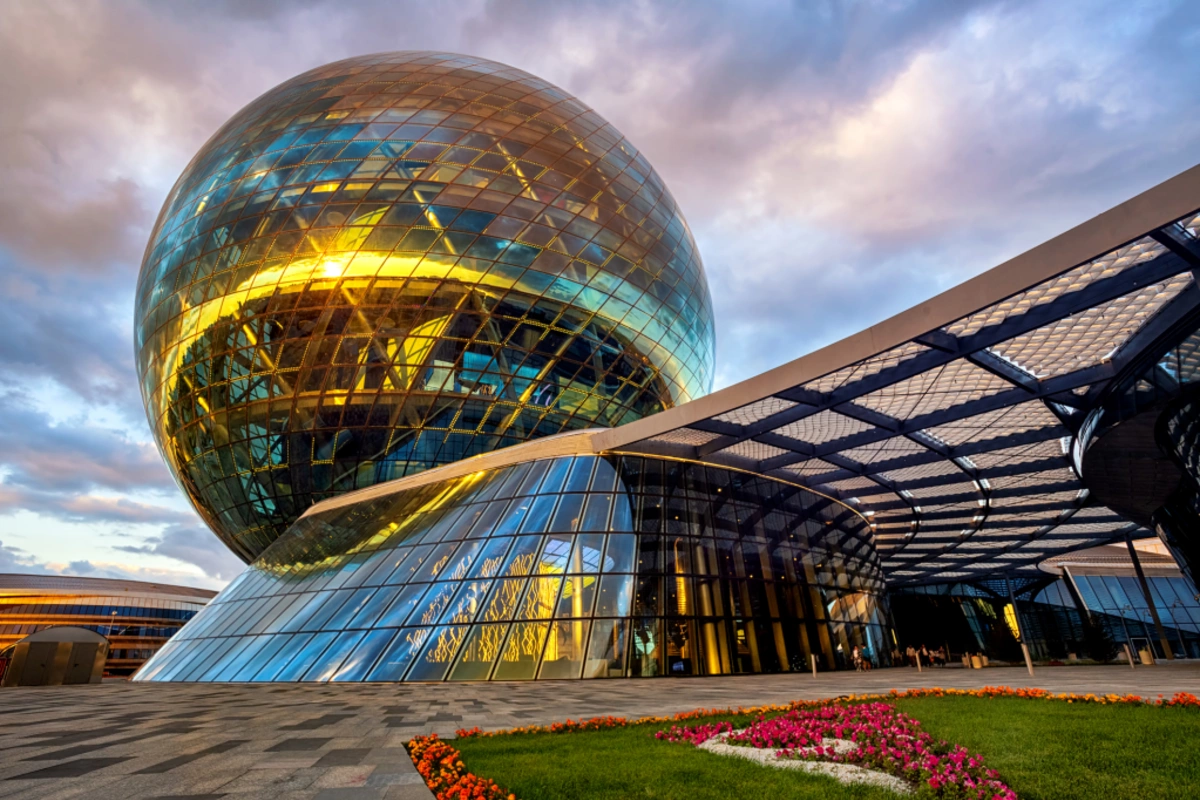
The Nur Alem sphere at the AIFC campus in Astana at sunset
Astana International Financial Centre

Open your short-term lending fund at AIFC.

We establish and operate licensed fund managers in the Astana International Financial Centre: an English common-law jurisdiction with a fintech sandbox that licenses in two to three months, 0% tax on qualifying income until 2066, and a regulator that already provides for tokenised fund units.

2–3
Months to licence
0%
Tax on qualifying income to 2066
US$50k
Minimum subscription, Exempt Fund
Up to 2 yr
Sandbox licence under the FinTech Lab
Why this exists

Direct investment doesn't work for many private investors

An individual who wants to put US$50,000 behind a producer in Vietnam, Indonesia or Uzbekistan has two conventional choices, and both of them fail for reasons that have nothing to do with the business being good.

Option oneTake equity

Months of process, then a year of waiting

Registration first
Foreign ownership means an investment certificate and amended company registration before a dollar can arrive. One to three months in most jurisdictions, longer where the sector is conditional.
Lawyers on both sides
Share subscription, shareholder agreement, local counsel, translations, notarisation. Fees that make no sense against a US$50,000 cheque.
Money comes out once a year, if at all
Dividends wait for audited year-end accounts, tax clearance and a notification to the authorities. Nothing mid-year, whatever the business earned.
No exit date
Selling shares needs a buyer and a transfer process. There is no maturity.
Governance you didn't want
Now you are a shareholder in a foreign private company, with the reporting and the minority position that come with it.
Option twoLend directly

The right instrument, the wrong plumbing

Fast and finite
A short-term loan lands in weeks, repays on a fixed date, takes no equity and needs no buyer. On the face of it, exactly what the investor wants.
But the borrower can't take fifty of them
Each foreign loan is separately documented, separately registered with the central bank and separately reported. Fifty lenders is fifty of everything.
And most investors have no company
An individual lending across a border is an AML problem for the receiving bank before it is anything else.
Security doesn't scale
Fifty lenders can't each hold a charge over the same receivable, and none of them individually can enforce one.
Nobody is watching
No agent, no collection account, no reporting. Each investor is alone with a foreign borrower.

The missing piece is aggregation.

A short-term loan is the correct instrument. It just has to arrive as one loan, from one lender, with one registration, one security package and one collection account, funded by many investors who each hold a transferable interest in it. That is a fund, and a fund needs a licensed manager. Building and running that manager is what we do.

The model

How the money moves

One licensed vehicle between many investors and each borrower. Everything else in this structure follows from that shape.

Investors
Professional investors
Subscribe for units, in USD or via a licensed stablecoin venue. Bear the credit risk, disclosed.
subscribe
AIFC
Manager and fund
Licensed manager runs a fund that is the single lender of record. Holds security, collects, distributes.
180-day loan
Borrowers
Producers and SMEs
One loan agreement, one registration, one repayment channel per borrower. Secured on receivables.
Limited recourse

Each note series or unit class is linked to a facility. If the loan pays, the series pays. The manager's own capital is never the source of repayment, which is also what keeps the manager out of deposit-taking.

Independence

The manager is not directly owned by a borrower. That removes transfer-pricing exposure on the loan, removes the governance conflict at authorisation, and is what investors' advisers look for first. Indirect ownership is not a workaround: arm's-length rules can still apply where a borrower controls the manager through an intermediate holder.

General mandate

Written for multiple borrowers from day one. A fund that lends only to one party is a captive whatever its licence says; the second borrower is what makes it a credit business.

What we do

A licensed lending fund, built and run for you

Lending money that belongs to other people requires a licence, and a licence requires a company, a resident executive, a compliance function and a regulator willing to approve all three. We build that at the Astana International Financial Centre, take it through the FinTech Lab in two to three months, and then run it. What stays with you is the part that should: your borrowers, your credit decisions, your investors.

01

Assess

We map your borrowers, investors and cash flows, confirm the structure is one AIFC can licence, and price it: licence route, capital, timeline and annual running cost, with the numbers attached. If it isn't a fit, we tell you before you spend anything.

02

Establish

Incorporation of the manager and the fund, the FinTech Lab application, conflicts framework, compliance manual, fund documents, loan and security templates, bank onboarding, through to authorisation.

03

Operate

Our team member holds the resident senior executive role the regulator requires, oversees compliance, onboards investors, handles reporting and distributions, and documents each facility.

Who it's forOperators, arrangers, family offices
Producers in agriculture, aquaculture and trade who need recurring working capital and have investors ready to lend. Arrangers and family offices who want a regulated vehicle for private credit into Southeast and Central Asia. Anyone whose investors hold stablecoins and whose borrowers need dollars.
What it isn'tNot a shortcut, not advice
Not a way to take deposits or run an unlicensed pool: investors hold units in a licensed fund and bear the credit risk, disclosed. Not a shortcut around the borrower's home-country rules, which we build for rather than around. Not legal or tax advice; we coordinate AIFC-registered counsel and local counsel, and they sign the opinions.
The Centre

A country within a country, under English law

The AIFC was created by constitutional statute in 2015 and opened in July 2018 on the EXPO 2017 site in Astana. It has its own legal system based on English common law, its own court and arbitration centre with judges from England and Wales, its own regulator, and its own tax and currency regime, all operating in English.

It is one of a small number of financial centres worldwide built on this model, alongside Dubai's DIFC, Abu Dhabi's ADGM and Qatar's QFC, and by some distance the least expensive of them to establish and operate in.

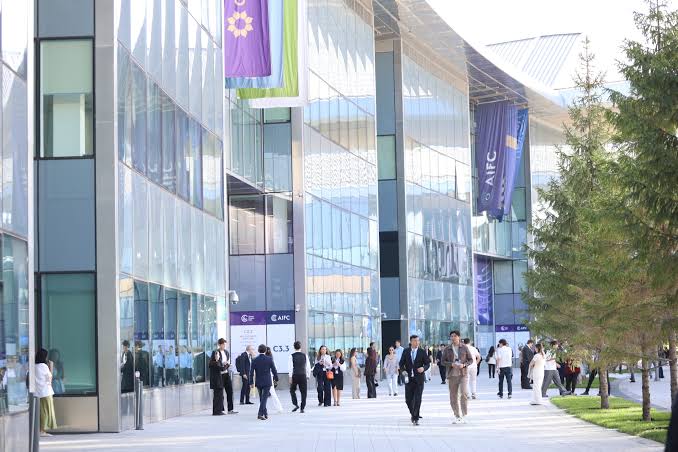
The AIFC campus walkway with participants and AIFC banners
AIFC campus, Mangilik El Avenue, Astana
Legal system
English common law
AIFC acts are based on the law of England and Wales; Kazakh law applies only where AIFC law is silent.
Courts
AIFC Court and IAC
Independent court and International Arbitration Centre, English-language, judges drawn from the English bench.
Regulator
AFSA
The Astana Financial Services Authority licenses and supervises participants, including the FinTech Lab.
Tax
0% to 2066
Corporate and personal income tax exemptions on qualifying financial and ancillary services, subject to substantial presence.
Visas
Up to 5 years
AIFC participants hire foreign staff without work-permit quotas; the Expat Centre handles visas and registration.
Currency
Any currency
Participants transact in the currency of their choice under the AIFC's own currency regime.
Tokenisation
Frameworks in force
Security Token Offering framework (2024), Investment Token framework (2024) and provision for tokenised fund units.
Digital assets
Licensed venues
AFSA-licensed exchanges with banking channels; AFSA itself is piloting USDT and USDC for its own fees.
Language
English
Law, filings, court proceedings and regulator correspondence.
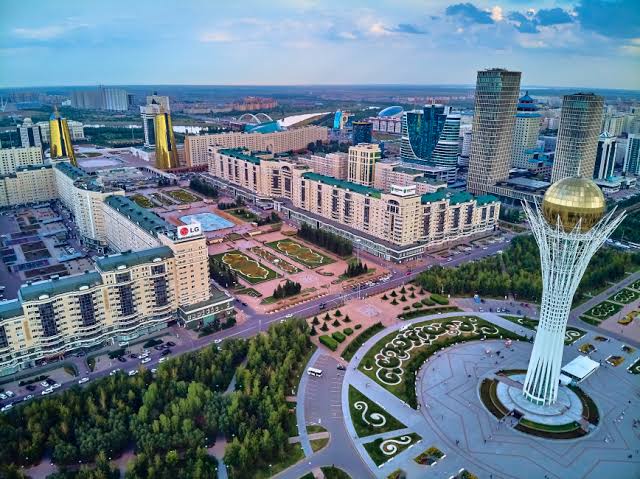
Aerial view of central Astana with the Baiterek tower
Central Astana, Baiterek tower
Astana

The city around it

Kazakhstan's capital since 1997, purpose-built, and the largest economy in Central Asia. The AIFC campus occupies the EXPO 2017 grounds, a short drive from the government district and the airport.

Direct flights reach Hanoi and Da Nang, as well as Dubai, Istanbul, Frankfurt, Seoul, Beijing, Tashkent and most CIS capitals. The single time zone, UTC+5, overlaps the Gulf morning and the East Asian afternoon. Office space on the AIFC campus starts around US$20 per square metre per month, so a registered desk for a small manager costs a fraction of Dubai or Singapore. Cold winters, warm summers, and a resident international community built up around the Centre since 2018.

Fund options

What AFSA lets you build

A fund at AIFC is two entities: a licensed manager that runs it and a separate fund that investors own. AFSA's Collective Investment Scheme rules offer two fund categories and several legal forms.

Fund typeWho can investHow it's offeredRegulatory treatment
Exempt Fund Professional Clients only, minimum subscription US$50,000 Private placement; no public offer, no prospectus Notification-based; lighter ongoing requirements. The right vehicle for a lending fund.
Non-Exempt Fund Retail and professional investors Public offer with an approved prospectus Full registration and supervision; higher capital and governance.
Legal formsCompany, partnership or trust
Investment company, limited partnership, or trust; open- or closed-ended. For a credit fund we typically use a company with limited-recourse note series or unit classes linked to each facility.
Related permissionsCredit, administration, digital assets
Providing Credit, Arranging a Credit Facility, Providing Fund Administration and the digital-asset activities each sit under their own permission. Tokenised units are securities, so they stay inside the manager's licence with no second entity.
FinTech Lab

The sandbox that licenses in a quarter

The FinTech Lab is AFSA's live regulatory sandbox: a real licence, with real clients, granted to firms testing a new model, on lighter capital and substance terms and a defined path to full authorisation at the end of two years.

Capital is evidence of twelve months' operating expenses rather than the standard base requirement. Fees are charged at 10% of the standard schedule, with a modest review fee on submission. Time is two to three months from a materially complete application, on a rolling basis. The licence runs two years, extendable, then transitions to the full regime.

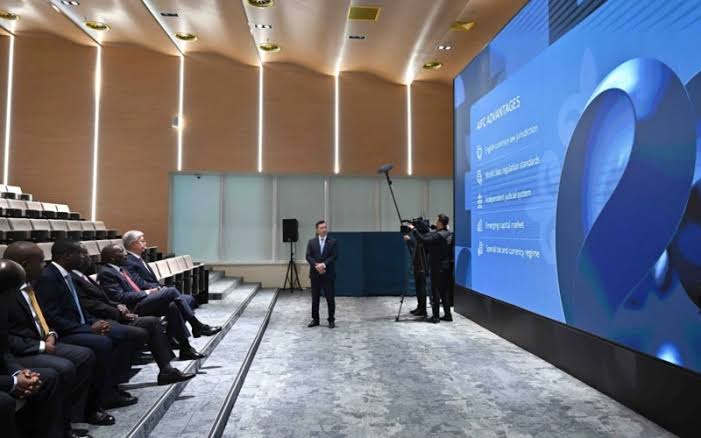
A briefing in an AIFC auditorium with AIFC advantages on screen
AIFC briefing, Astana

A plain lending fund does not pass the innovation gate.

AFSA has become more selective about Lab admissions. "We pool money and lend it" is a finance company, not a fintech. What passes is a platform, and a credit fund built the right way is one. We frame the application around five things that are all genuinely part of the model.

  1. Digital onboarding and KYC of cross-border professional investors, with nationality screening at the door.

  2. Subscription in USD or stablecoin through AFSA-licensed conversion venues; the fund receives fiat.

  3. Tokenised, transferable units issued to whitelisted holders on a registry the manager controls.

  4. Borrower telemetry streamed to holders of each series: production data, milestones, sale confirmation.

  5. Distributions and secondary transfers between whitelisted investors, first inside the fund's own register.

Tokenisation

What tokenisation actually means here

The word carries a lot of noise. In a licensed fund it means one specific, unglamorous thing: the register of who owns what is kept on distributed-ledger technology instead of in a spreadsheet, and the entries on it can be transferred between approved holders.

What it isA unit, in digital form
Each token is a unit in the fund, or a note in a series tied to one facility, issued by the licensed fund. Under AFSA's Security Token framework it is "a digital representation of a Security or Unit". It is a security, governed by securities rules, exactly as a paper unit would be.
What it is notNot a coin, not a commodity
Not a cryptocurrency, not a claim on physical goods, not a bet on a price. Because tokenised units sit in the securities regime rather than the digital-asset regime, the manager issues them under its existing licence, with no separate digital-asset permission and no second entity.
Who can hold itWhitelisted professionals only
Transfers are restricted to investors who have passed KYC and been added to the register, which the manager controls. It is the opposite of an open market: the technology enforces the restriction rather than removing it.

Why it suits agriculture and aquaculture in particular

Most tokenisation projects struggle to explain what problem they solve. In seasonal production lending the fit is unusually good, for four reasons that come from the crop cycle itself.

01

The asset is a season, not a company

A shrimp cycle runs 180 days. A rice or coffee harvest has a date. Lending against production means many short, self-liquidating facilities rather than one long exposure, and each one is naturally its own series: this pond, this harvest, this maturity. Tokenised series make that granularity administrable. Fifty investors across eight harvests is a spreadsheet problem in a conventional fund and a non-problem on a register.

02

Investors want to choose their exposure

Someone lending into aquaculture usually has a view: this producer, this region, this species, this season. A blended book takes that choice away. Series-level units give it back, and let the investor hold a specific, identifiable facility rather than a share of everything the fund has ever done.

03

The underlying generates real data

Ponds and fields are measured constantly: stocking density, survival rate, feed conversion, biomass, water quality, harvest weight, sale confirmation. That telemetry can be streamed to the holders of the series it belongs to. Very few private credit assets produce a verifiable operational signal between origination and maturity. Production agriculture does, and it turns a blind six-month wait into something the investor can watch.

04

The lockup is the expensive part

A large share of what investors demand in emerging-market production lending is not credit risk, it is illiquidity: money committed for a full cycle with no way out. A transferable unit, even one that can only move between whitelisted professionals, puts a floor under that. Every point of required return that liquidity removes is a point the borrower does not pay.

Built, not invented

The registry, whitelisting and transfer controls come from a licensed white-label provider in the centre. The manager answers to the regulator for the infrastructure, so we use providers who have already met its standards.

Start in the register

At launch, transfers happen inside the fund's own register, approved by the manager. Secondary trading on an AFSA-licensed venue comes later, when volume justifies it.

Where it does not help

Tokenisation does not change what a regulator permits, widen who may invest, or move money a borrower's central bank will not release. It improves distribution and liquidity. The structure underneath still has to be sound.

Process

From engagement to first drawdown

Weeks 0–2

Engagement

Assessment delivered. Local counsel engaged in the borrower's country. Owners' source-of-funds file assembled for the regulator.

Weeks 2–6

Incorporate and file

Manager and fund incorporated and capitalised. Independent director appointed. Conflicts framework and fund documents drafted. Lab application filed.

Months 2–4

Licence

AFSA review and authorisation. Bank account opened. Tokenisation registry and investor onboarding live.

Months 4–5

First pooled drawdown

Investors subscribed, first facility documented and secured, funds wired to the borrower's registered loan account.

Compare

AIFC against the alternatives

For a first fund of a few million dollars, the difference between centres is almost entirely people and capital: how many resident professionals you must employ, and how much regulatory capital must sit idle before you lend.

AIFC · FinTech LabDIFC · Innovation Testing LicenceSingapore · A/I LFMC
Time to licence2–3 months4–6 months4–6 months
Regulatory capital12 months' operating costNegotiated; anchored to US$70kS$250k plus 120% of risk requirement
Resident staffLight2 officers, combinable2 full-time resident professionals
Self-sustaining at~US$3.2m loans outstanding~US$5.2m~US$10–13m
Tax on the manager0% to 2066 with substance9%; 0% on qualifying fund income17%; fund incentives need S$200k local spend
Tokenised unitsFrameworks in forceThrough the sandbox by ruleMost mature, under full licence
Stablecoin subscriptionsLicensed exchanges with bank channelsLicensed venues, direct to USDLegal; banks are the obstacle
Investor recognitionNeeds a sentence of explanationStrongStrongest in Asia

DIFC becomes the better answer when investors are mostly Western or Gulf and the fund will exceed US$5 million in its first two years. Singapore becomes the better answer when investors are Singapore-based and the fund will exceed US$10 million. Below those thresholds — where a first fund almost always sits — AIFC's cost base is decisive. We build and run at AIFC only. If your fund belongs somewhere else we will say so, but we will not be the ones to take it there.

Questions

Things clients ask first

Do I have to move to Astana?

Someone does. AFSA requires a resident senior executive, and the tax exemption requires substantial presence: real staff and expenses commensurate with the business. Under our operating retainer, our team member holds the resident senior executive role, so you don't have to relocate. If you'd rather hold it yourself, Astana is one of the cheaper places on this list to satisfy a "be here" requirement.

Can investors subscribe in USDT?

Yes, with one rule: the fund never holds tokens. Investors send USDT to an AFSA-licensed exchange or OTC desk, which does its own KYC and source-of-funds checks, converts, and pays fiat to the fund's account. Those venues have established channels with Kazakh banks, and AFSA itself is piloting USDT and USDC for its own fees. Converting for the fund's own account keeps the manager out of the digital-asset licensing regime entirely.

Can a borrower own the manager?

It's possible but it's the hardest version to license. A manager owned by its own borrower has a conflict the regulator assesses at authorisation, related-party transfer-pricing exposure on the loan, and a harder story with investors. It can be done with an independent director holding the deciding vote on that borrower's facilities, a cap on the borrower's share of the fund, and full disclosure. Where the borrower has no funds outside its home country, the cleaner path is an independent manager with an option for the borrower's owners to buy in later.

What about the borrower's own country?

Nothing at AIFC changes the rules where the money lands. A loan into Vietnam, for instance, is a short-term foreign loan under the State Bank's regime: a registered foreign-loan account, a report or registration, a 5% withholding on interest, and a 20% statutory interest ceiling where Vietnamese law governs. We build the facility documents to those rules with local counsel, once, and reuse them for every borrower in that country.

Is banking a problem in Kazakhstan?

Outbound USD wires from Kazakh banks to Southeast Asia work; we've tested them. Stablecoin conversion runs through licensed exchanges with existing bank channels. For clients who want a second banking relationship outside Kazakhstan, an AIFC company can hold accounts abroad.

What happens at the end of the two years?

The FinTech Lab licence transitions to full authorisation, which means the standard base capital and substance requirements, applied to a firm that by then has two years of operating history, audited accounts and a book. We plan the graduation from day one, because investors' advisers will ask.

Why does the second borrower matter so much?

Three reasons. A fund that lends only to one party reads as a captive to the regulator and to investors. Loans to unrelated producers become the pricing benchmark that protects the first borrower's rate. And a manager at AIFC only covers its running cost at about US$3.2 million of average loans outstanding, which one borrower rarely reaches alone.

From the founder

Why I started Cyan

Joe Ruelle, founder and chief executive of Cyan

I spent several years at Google working with enterprises across developing Asia, helping them scale their infrastructure. I learned quickly that one of the hardest limits on scale had little to do with the business itself. It was the raw difficulty of moving investment capital in, and moving returns back out.

I opened Cyan to offer an alternative built on aggregated short-term lending, so that companies in emerging Southeast Asia can move capital internationally at the same speed they move it at home.

Joe Ruelle
Founder and CEO
Start

Start with an assessment

Tell us who borrows, who invests, and where the money has to land. We'll come back with a costed AIFC route — licence, capital, timeline and annual running cost — and a plan for getting there.

We reply within two working days.

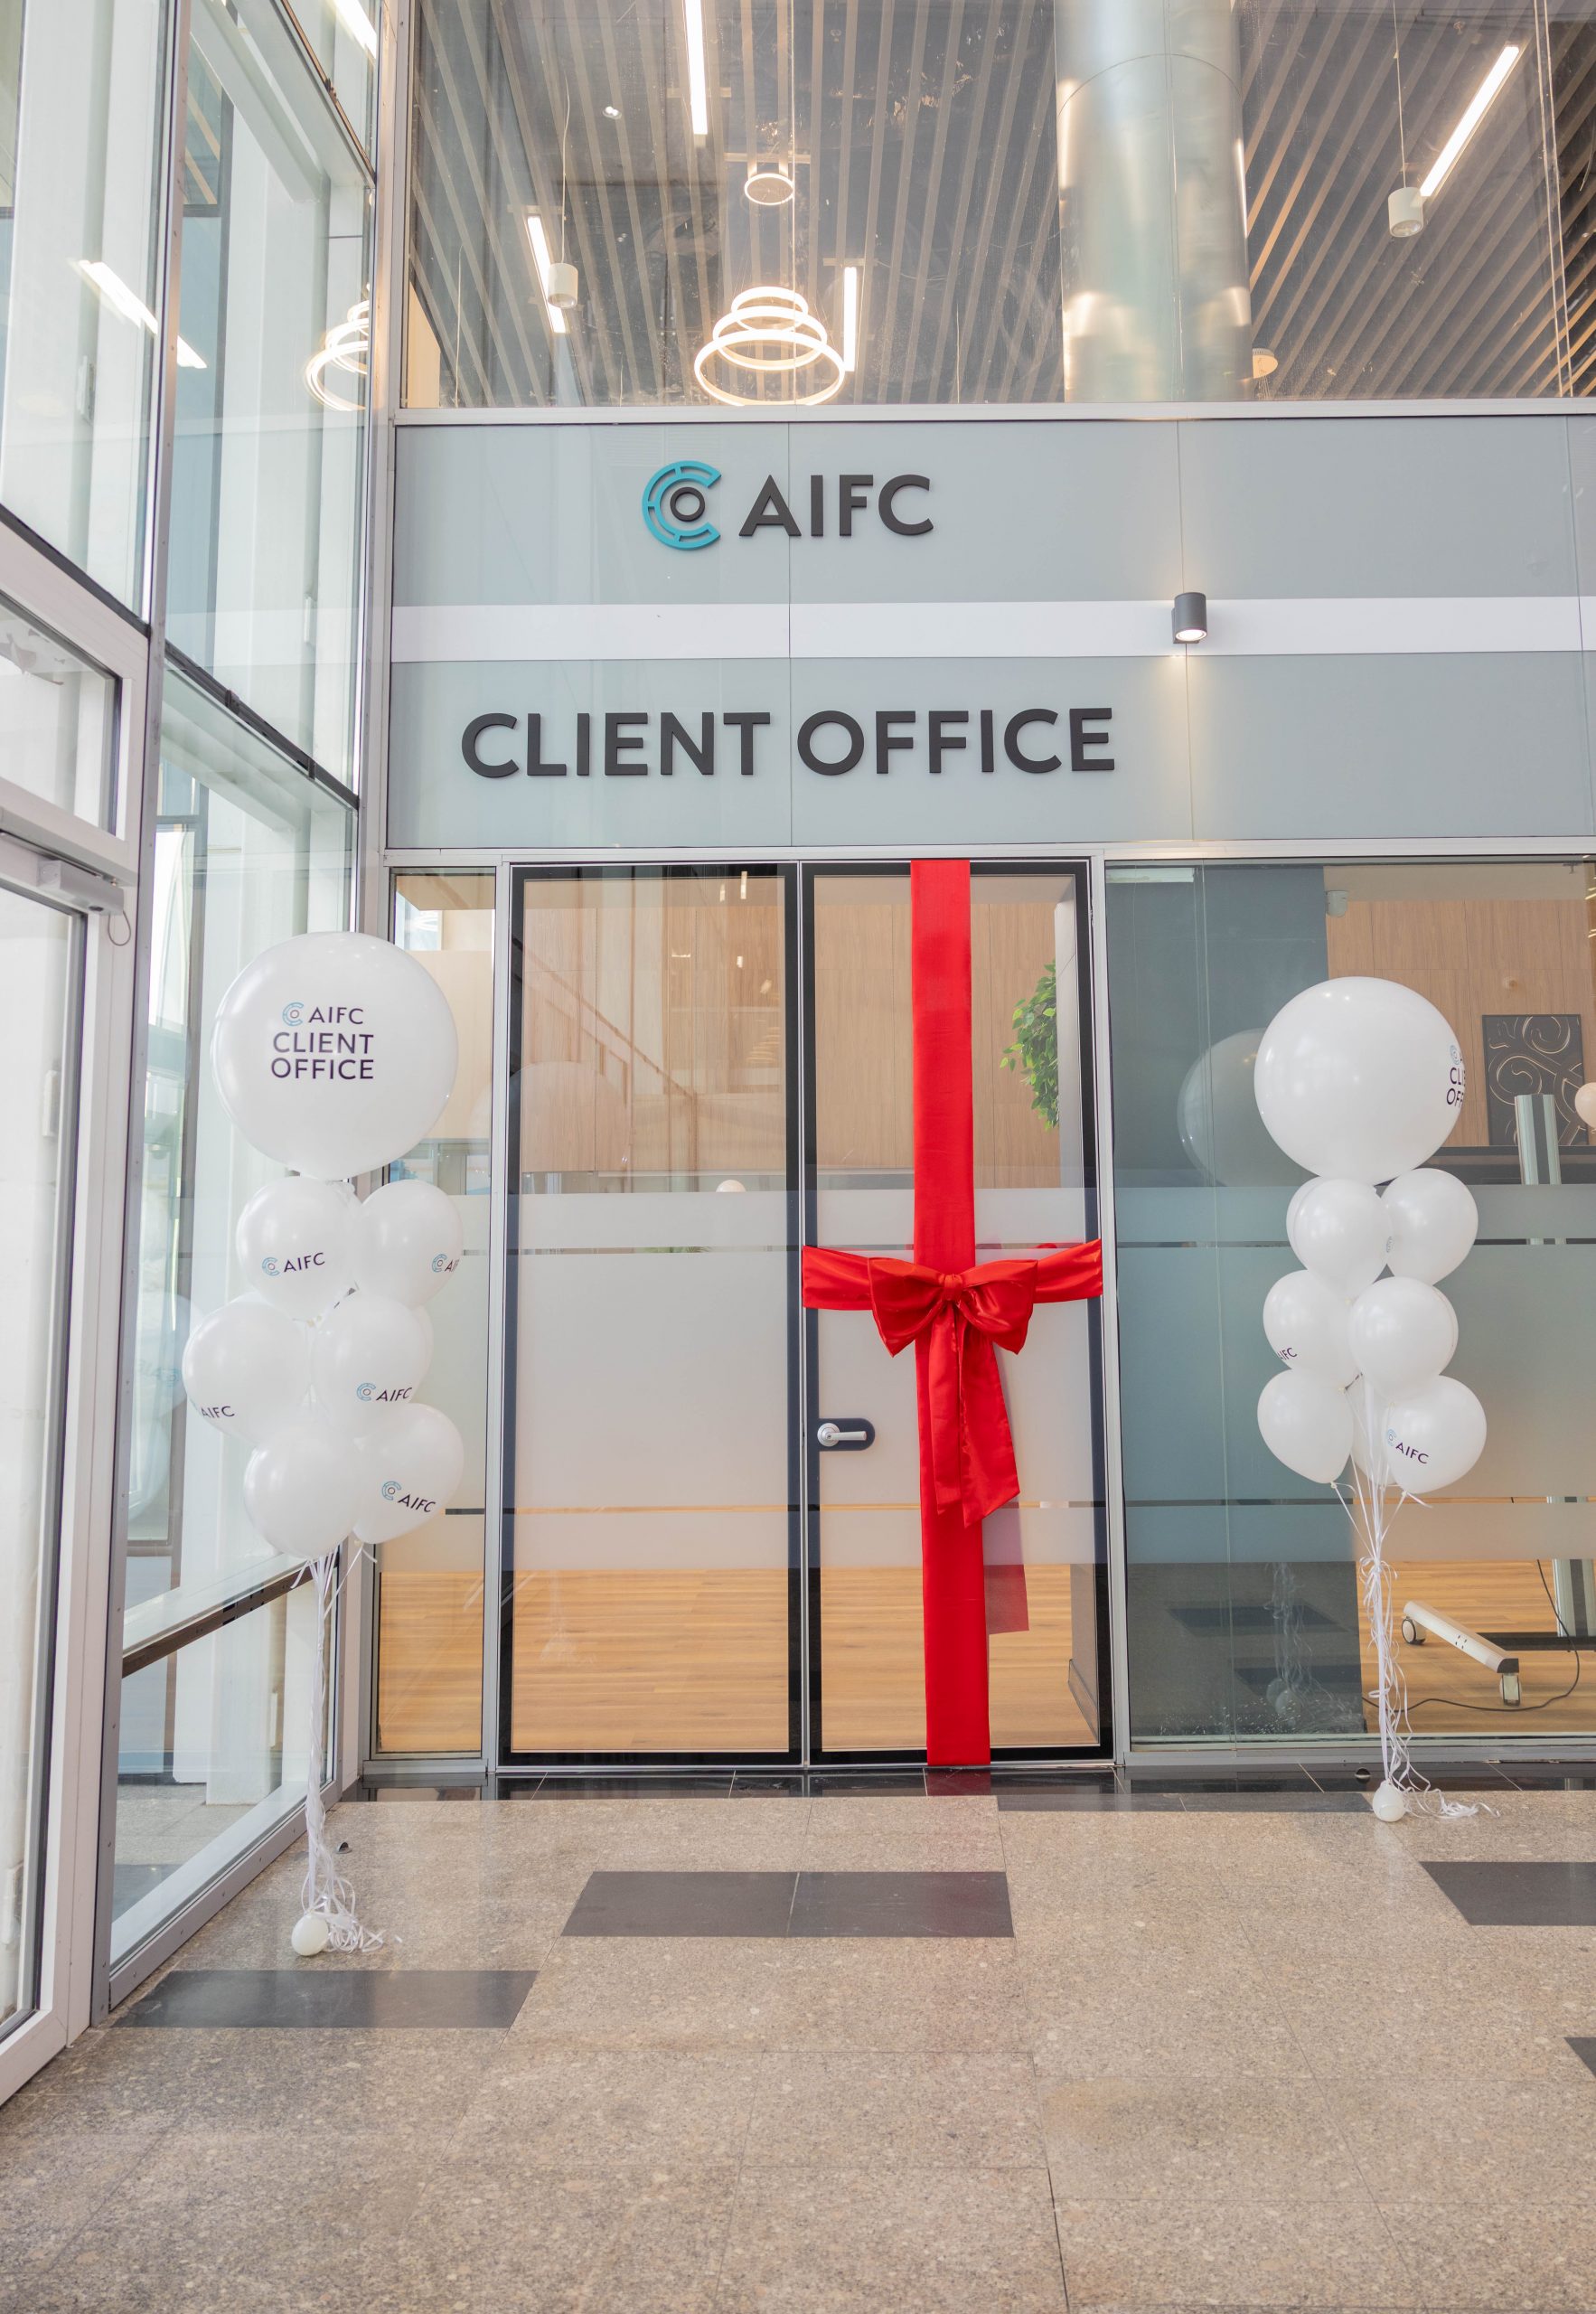
The AIFC Client Office entrance on opening day
AIFC Client Office, Astana